2025-10-03 20:01 UTC — West Texas Intermediate remains heavy into early October, with a tactically bearish skew but low signal strength. Our WTI sentiment 25% confidence flag reflects a modest tilt rather than a high-conviction call, as price gravitates around the 61-handle and intraday means cluster near 60.90. With a light macro calendar, the tape is likely to be dominated by microstructure and technical flows, keeping a range trade in focus unless liquidity pockets are breached.
Macro drivers
The near-term macro backdrop appears neutral-to-quiet for crude futures. There are no scheduled high-impact events in the next 24 hours, limiting top-down catalysts and raising the odds that positioning, risk management, and intraday flow dictate direction. Expected volatility is balanced (EVR: balanced), suggesting options markets are not pricing outsized directional risk over the immediate horizon.
Correlations to major macro anchors are muted, underscoring an idiosyncratic phase for oil. The recent rolling correlations show: US 10-year yields at -0.18, USDCNH at -0.158, EURO STOXX 50 at +0.116, FTSE 100 at +0.112, and USDJPY at +0.105. None are strong, and the signs split, diluting cross-asset signal power. For asset allocators, this argues against leaning too heavily on rates or dollar impulses to drive crude in the very near term.
Key asset anchors
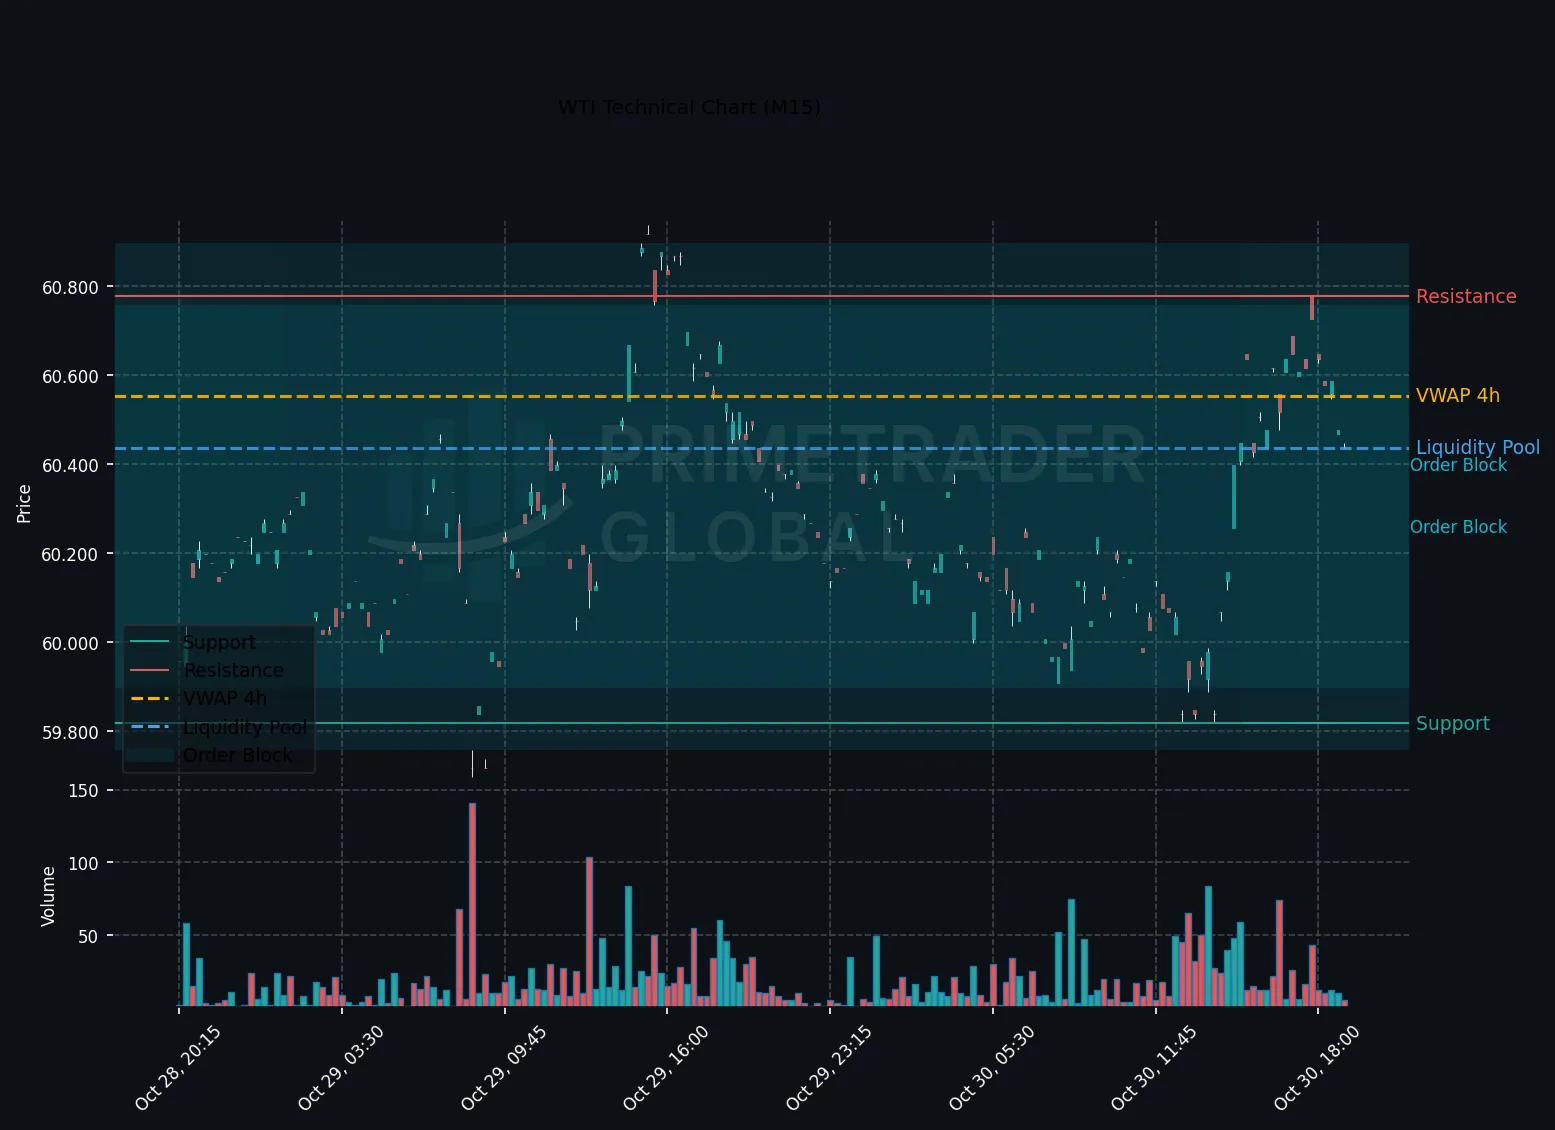
Technically, WTI’s short-term structure is defined by nearby liquidity and value references:
- Liquidity pool: 61.037 — a likely magnet and stop cluster where whipsaws can occur if probed.
- Order blocks: 60.847 and 60.707 — layered supports where passive bids may reside; a decisive break would mark a regime shift lower.
- VWAPs: Daily 60.9255 and 4H 60.8926 — intraday fair value concentrated just under 61.00, reinforcing the range dynamics.
- Cumulative VWAP: 62.9821 — multi-session value above spot, a tactical sell zone on approach if momentum remains tepid.
Risk-reward skew currently favors the downside with an asymmetry that matters for trade construction: Up = 0.73 versus Down = 1.36. While not a forecast in itself, this skew aligns with a WTI bearish forecast October 2025 framing that prioritizes fading rallies into overhead value rather than chasing breakouts absent catalyst.
Cross-asset implications
With correlations muted, cross-asset spillovers are likely to be selective:
- Equities: Mild positive links to EURO STOXX 50 and FTSE 100 (+0.116 and +0.112) imply limited equity beta transmission. Energy-heavy indices may see marginal support if WTI stabilizes at value, but a break below 60.70 would likely weigh on energy sector sentiment.
- Rates and FX: The weak negative tie to US 10-year yields (-0.18) and modest positive tilt to USDJPY (+0.105) suggest dollar and rate moves are secondary drivers for now. For the petro-FX complex, the light tape reduces the impulse to CAD/NOK, placing more emphasis on domestic drivers. Investors considering a WTI forex forecast 2025 lens should mark today’s low linkage as a near-term caveat rather than a structural shift.
- Volatility and positioning: A balanced EVR and compressed cross-asset betas argue for options structures that monetize range rather than convexity, unless price migrates into illiquid pockets (notably below 60.70) where realized vol can spike.
Outlook
The base case is range-bound action until a catalyst dislodges price from clustered value. The WTI technical outlook daily favors a fade-the-rally bias into 62.80–63.10 (around the 62.9821 cumulative VWAP) with tactical stops placed just beyond nearby liquidity sweeps. On the downside, a clean break and hold below the 60.847/60.707 order blocks would open the path toward round-number psychology at 60.00 and then legacy pockets lower. Conversely, sustained acceptance above 63.00 would neutralize the bearish lean and re-open 64.50–65.00.
Strategy framing for institutions: With WTI trading strategy update signals only at 25% confidence, risk should be sized accordingly. For directional participants, skew supports shorting strength into cumulative value with defined stops. For options users, balanced EVR endorses put spreads funded by tight call calendars, or gamma-light structures that benefit from mean-reversion while retaining tail protection. Portfolio hedgers might prefer staggered entries near 62.80–63.10 and again on a break of 60.70 to avoid concentration risk.
Key checkpoints: Watch for liquidity grabs around 61.037 to set intraday tone; observe whether bids reassert at 60.847/60.707 on any flush. Absent fresh macro impulse, the market is likely to respect these references. Should realized volatility expand on a sweep-and-fail sequence, expect fast mean reversion back toward the 60.90 VWAP zone. If instead a sweep accelerates into acceptance below 60.70, shift the framework from range to trend and reassess exposure.
Bottom line: The tape is balanced-to-soft with low cross-asset guidance. A modest WTI sentiment 25% confidence tilt favors selling rallies into cumulative value and defending 60.70 as near-term pivot. Until the range breaks, discipline around execution and sizing will matter more than directional conviction.