2025-10-02 20:31 UTC — The AUS200 (ASX 200) enters October with a mild bearish bias and low conviction, hovering near pivotal ranges as traders position around a forecast Manufacturing PMI of 49.6 and a steady RBA cash rate profile at 3.60%. With risk-reward skewed to the downside and correlations tightening with European benchmarks, the index looks range-bound pending a catalyst, while sector rotation and AUD rates dynamics shape near-term outcomes.
Macro drivers
The week’s narrative is defined by domestic activity gauges and policy signaling, set against a fragile global risk backdrop:
- Manufacturing PMI: Consensus near 49.6 (prev. 49.4) points to ongoing mild contraction. A sub-50 print reinforces cautious capex and inventory management, pressuring cyclicals and industrials. Watch new orders and supplier delivery times for forward momentum cues. AUS200 reacts to Manufacturing PMI when forward-looking components shift inflection.
- RBA Policy: Markets broadly positioned for no change at 3.60%, keeping financial conditions restrictive in real terms. Statement tone on services inflation, wages momentum, and housing credit will be pivotal for November expectations. A hawkish hold risks front-end yield repricing and index multiple compression.
- China linkage: Australia’s terms-of-trade beta to China remains high via iron ore and bulk commodities. Any incremental stimulus chatter can cushion materials, but a soft PMI locally would highlight domestic demand weakness versus external tailwinds.
- Global rates and oil: Elevated global yields and sticky energy costs complicate disinflation. Higher term premia keep pressure on equity duration, particularly defensives with bond-proxy traits. Aussie long-end moves tend to mirror US/EU swings with a lag, shaping bank NIM expectations and equity risk premia.
Key asset anchors
Market microstructure and correlations frame near-term trading strategy:
- Bias and confidence: Model flags a bearish tilt with only 33% confidence. Event-Volatility Regime (EVR) is balanced, suggesting two-way risk into and out of data.
- Risk-reward profile: Up = 0.7 vs Down = 1.43 indicates asymmetry favoring downside follow-through if supports give way.
- Technical and liquidity map (reference levels): Liquidity pool at 8,929.78; near-term order blocks at 8,910.53 and 8,906.78. VWAPs cluster around current trade: Daily 8,928.45; 4H 8,920.23; cumulative 8,808.56. This clustering argues for range development before a directional break.
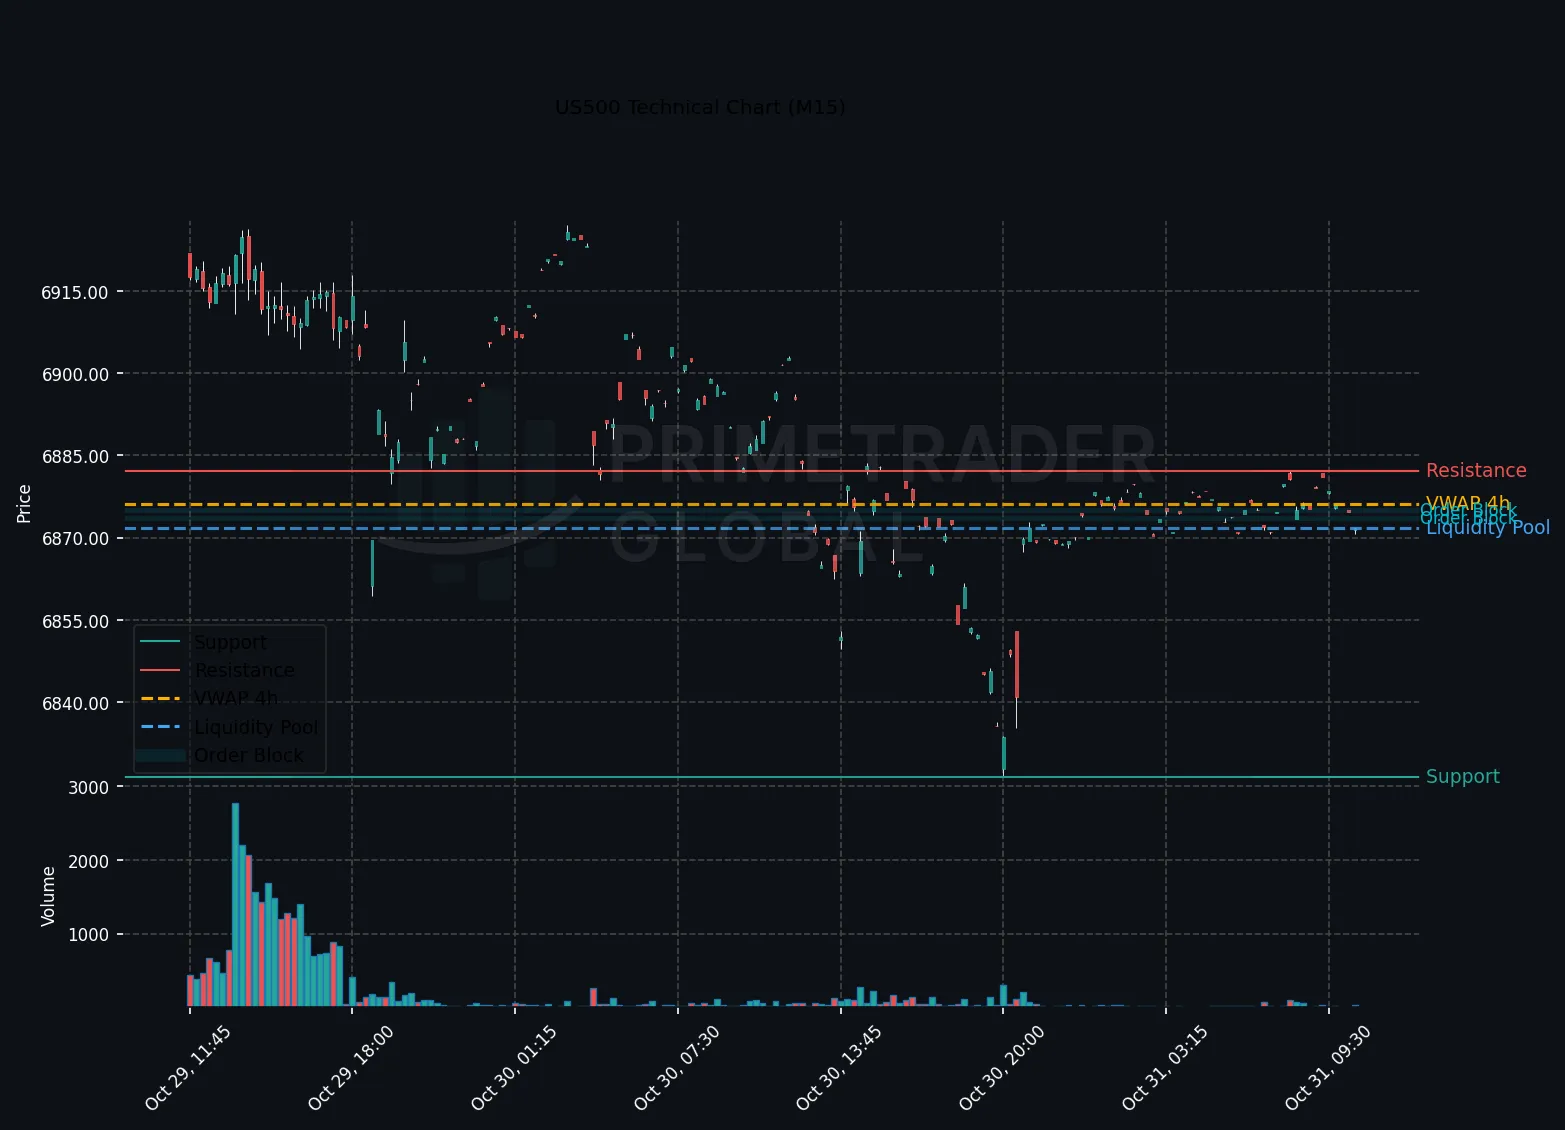
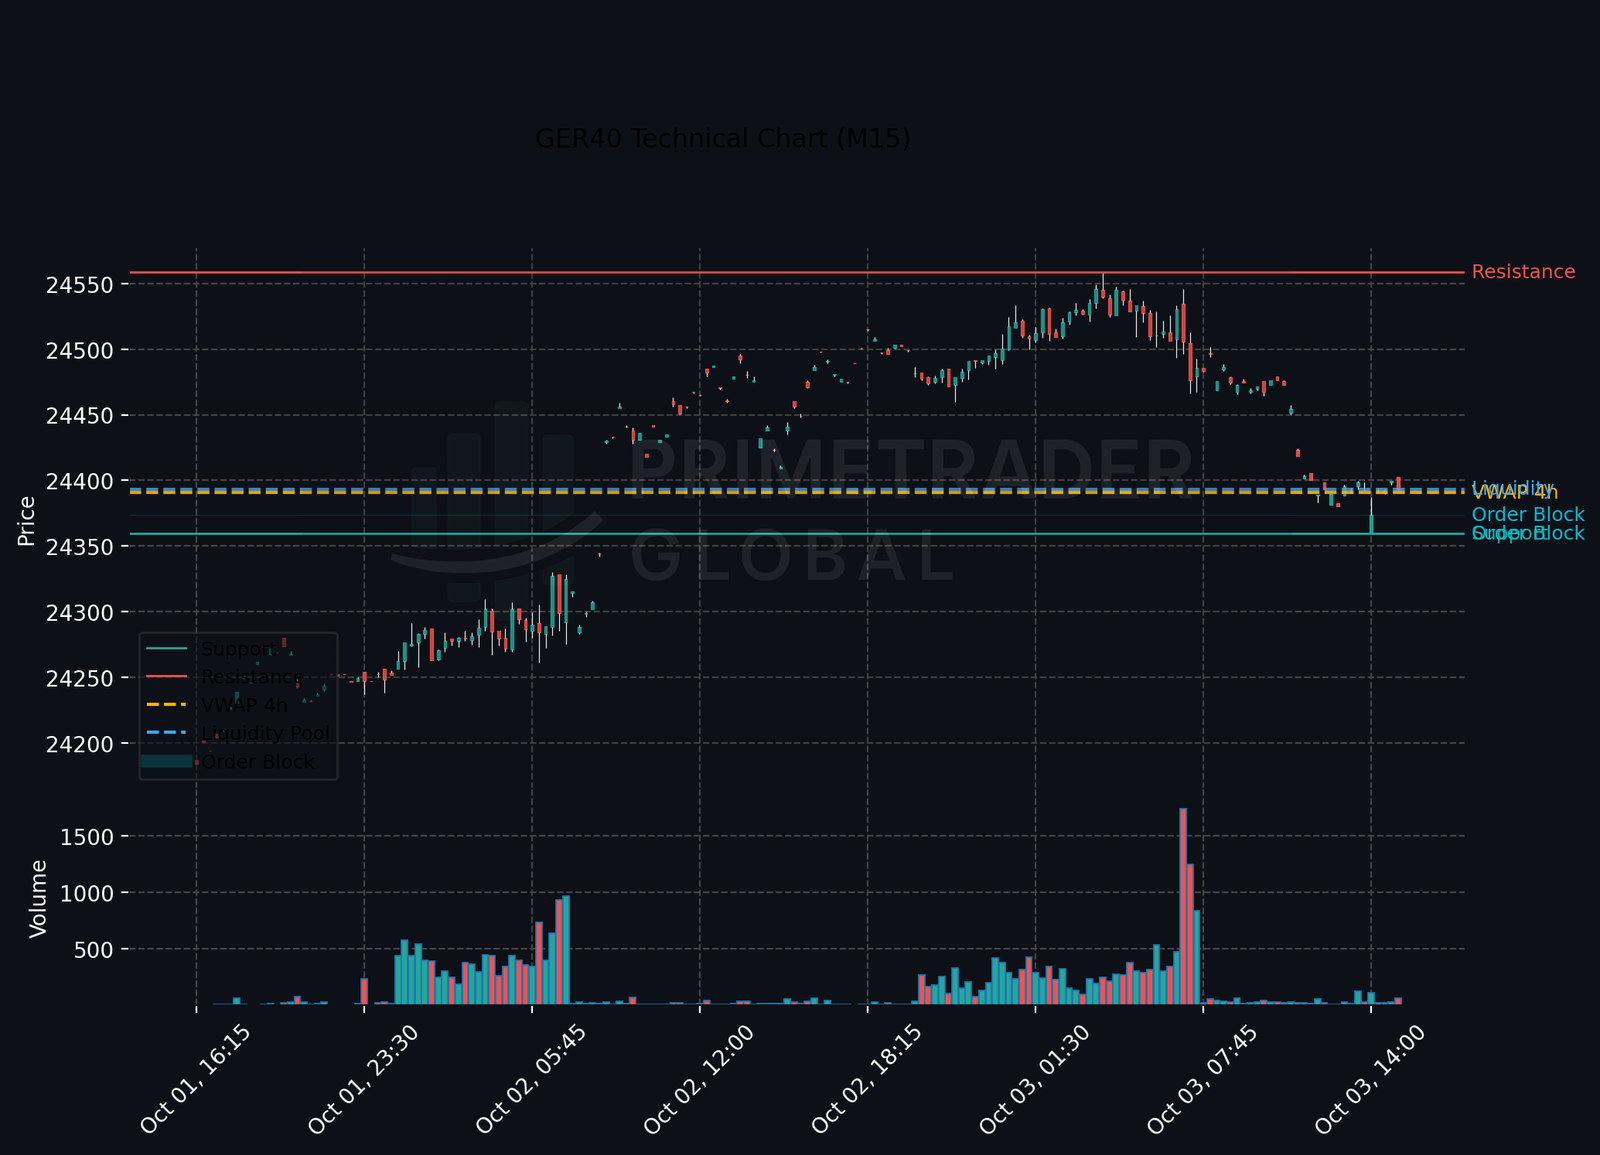
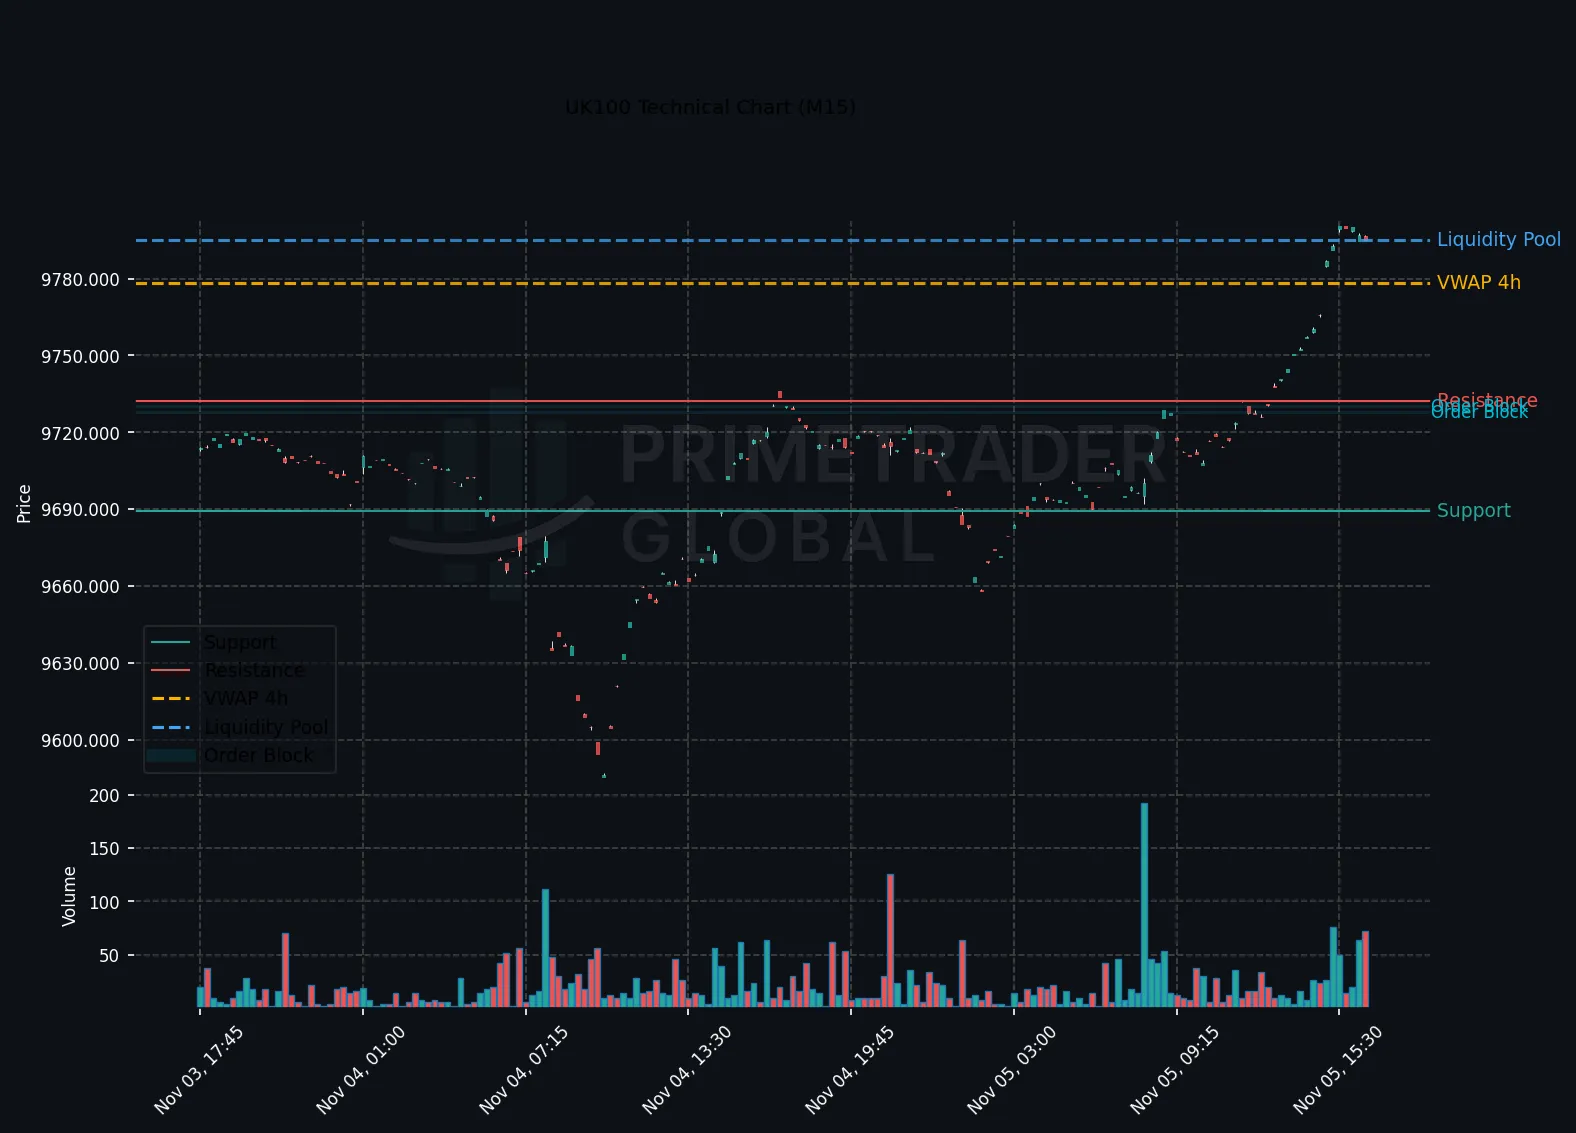
- Correlation matrix (rolling): EURO50 0.51, UK100 0.51, GER40 0.41, US500 0.39, US100 0.33. Positive but moderate betas imply overnight leads from Europe matter; US tech beta is smaller but non-trivial.
- Sectors: Banks are supported by firmer long-end yields but vulnerable to curve flattening. Materials hinge on China/iron-ore tone. Healthcare and staples face duration headwinds when yields back up.
Cross-asset implications
- AUD and rates: A PMI south of 50 with a steady RBA can weigh on AUD via growth expectations, while a hawkish statement could lift front-end yields and cap equity multiples. A softer AUD provides some earnings translation support for offshore earners but is not a panacea if domestic demand slows.
- Commodities: Iron ore sensitivity remains the swing factor for the AUS200 technical outlook daily. Any uptick in China steel output guidance can stabilize materials even if PMI disappoints.
- Global equities: With correlations to EURO50/UK100 above 0.5, European session tone is a useful hedge/risk signal. A weak Eurozone open could amplify local downside during the handover.
- Volatility: Balanced EVR argues for optionality strategies around event windows. Post-data, volatility decay is likely if prints land near consensus.
Outlook
Base case (range-bound, data-dependent)
Range-bound action likely until breakout. Expect the AUS200 to oscillate around the 8,910–8,930 zone where order blocks and VWAPs converge. Holding above 8,906.78 favors mean reversion toward the liquidity pool at 8,929.78. A clear daily close above the pool would invite a squeeze toward the 9,000 psychological handle, contingent on inline PMI and a neutral RBA tone.
Downside risk (skewed by RR profile)
A sub-consensus PMI or hawkish-leaning RBA language could crack 8,906–8,910 support, unlocking a test toward the cumulative VWAP near 8,808.56. Follow-through would likely be led by cyclicals and domestics. Given Down=1.43 vs Up=0.7, risk budgeting should assume deeper tails on breaks.
Upside surprise
A PMI beat above 50 or a dovish inflection in the statement could catalyze a topside break above 8,930, squeezing shorts into 9,000. Participation breadth from banks and miners would be needed for durability; otherwise, the move risks fading amid global yield headwinds.
Tactical positioning and strategy
- For AUS200 bearish forecast October 2025, lean short into rallies toward the 8,929–8,940 zone with tight risk, given the low-confidence signal and event risk.
- Flip risk if a daily close clears the liquidity pool with improving breadth and falling rates volatility.
- Cross-hedge via EURO50/UK100 given >0.5 correlation; avoid excessive US tech hedges due to lower beta.
- Watch AUD rates: a front-end pop without growth follow-through is typically equity-negative via valuation.
Bottom line: With AUS200 sentiment at 33% confidence and a balanced volatility regime, the index trades tactically heavy but remains data-dependent. The next few sessions hinge on the Manufacturing PMI print near 49.6 and RBA communication. Until a decisive catalyst emerges, respect the 8,906–8,930 pivot zone, manage for downside skew, and be prepared to switch if policy tone or growth signals break the stalemate. This is the actionable AUS200 trading strategy update for the week ahead.