2025-10-31 10:18 UTC
Lead Overview
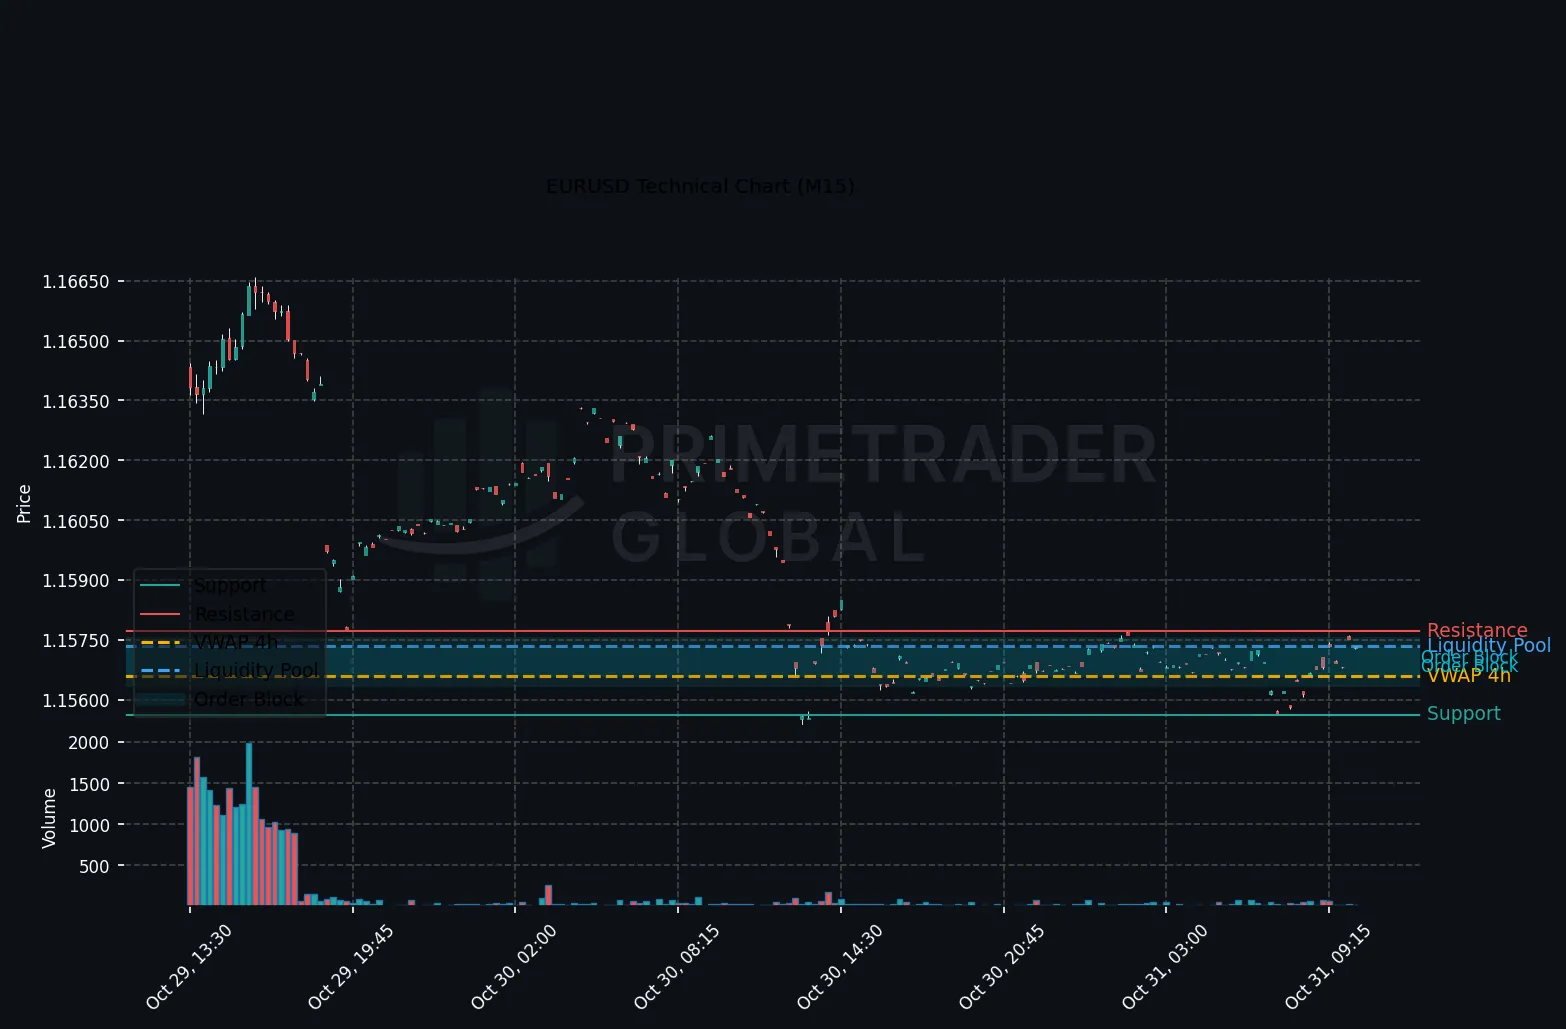
The European session sees EURUSD maintaining a neutral stance within a tight H1 range. A softer Italian CPI reading for October (+1.3% vs. +1.7% y/y expected) tempers expectations of near-term ECB tightening, reinforcing a neutral bias in EURUSD positioning. As markets digest these signals, intraday momentum remains restrained, particularly against a backdrop of broad yet cautious risk appetite.
Macro Drivers
Italy’s lower-than-anticipated HICP print emerges as a pivotal factor influencing euro dynamics. This miss potentially reduces the urgency for the ECB to enhance policy tightening, thereby moderating short-term bullish prospects for the euro. Meanwhile, global risk sentiment appears moderately positive yet lacks sufficient impetus to propel a decisive breakout in EURUSD.
Key Technical Anchors
The EURUSD trading range is currently bounded by support at 1.15536 and resistance at 1.16659. The absence of a breakout or breakdown from these levels underscores the pair’s current range-bound nature, with technical indicators aligning with this neutral positioning in the short term.
Cross-Asset Signals
Cross-asset flows suggest subdued volatility, with no significant shifts in correlation that could influence EURUSD. Equity markets exhibit a risk-on tilt, but without a corresponding move in currency pairs, indicating limited transmission of this sentiment into forex trading conditions.
Forward Outlook
Looking ahead, EURUSD’s price action remains contingent on developments in Eurozone economic data and broader risk sentiment shifts. Given the neutral technical setup, the pair is likely to continue trading between 1.15536 and 1.16659 over the short term. A break above or below these thresholds may offer clearer directional cues. As such, traders should remain vigilant for signs of evolving ECB policy expectations or unexpected macroeconomic catalysts that could disrupt the current equilibrium.
Prime Trader Global | AI Market Intelligence | All insights derived from factual market data.